We provide public adjusting services in Pennsylvania, New Jersey, Delaware, and Maryland. We work with homeowners and business property owners to review relevant policy terms, prepare claim records, and discuss supported differences with the insurance company.
Document the storm and the damage
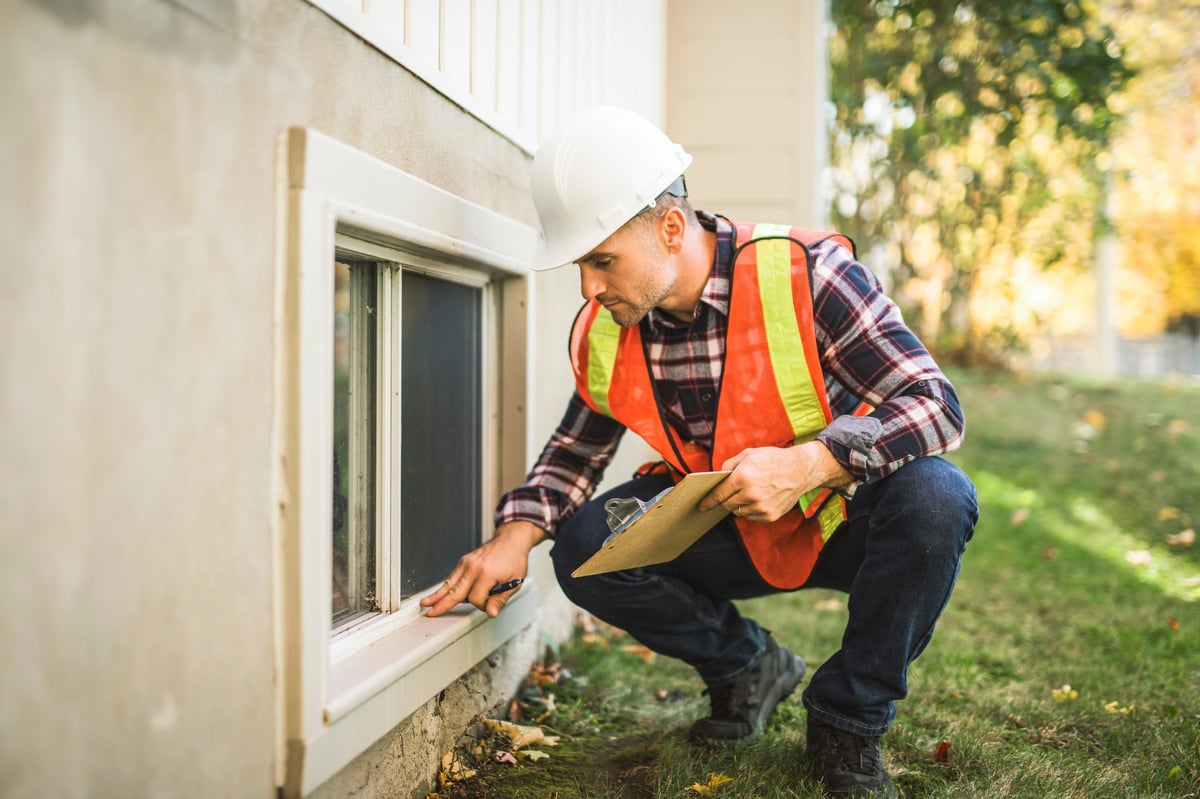
A claim file begins with a timeline. Record when the storm occurred, when you noticed the damage, and what steps were taken afterward. Include photographs from safe locations and any reports from qualified professionals who inspected or protected the building.
Depending on the property, the review may involve:
- Roof coverings, flashing, and visible openings.
- Siding, gutters, windows, and exterior doors.
- Interior areas affected by rain entry.
- Damage caused by fallen limbs or windblown objects.
- Temporary protection work and related invoices.
These are areas to review, not promises of coverage. Each claimed item must be considered under the policy.
Separate the causes of damage
One storm can lead to several kinds of loss. Wind damage, rain entering through an opening, and rising floodwater may involve different coverage questions. The fact that damage happened during a storm does not mean every part of it falls under the same policy.
We help organize the evidence about the cause and location of the damage. When more information is needed, we discuss the records that may clarify the issue. The goal is to describe the loss accurately without guessing about conditions that have not been confirmed.
Understand the estimate and deductible
Repair estimates should show the work included and the reasons for it. We review the estimates alongside photographs and other supporting records. Differences may concern the affected area, repair methods, quantities, or the policy's settlement terms.
Some policies include separate wind, hail, or hurricane deductibles. Roof coverage may also differ from coverage on other parts of the building. We review the terms so you can better understand how they affect the claim. Wear, maintenance issues, and excluded causes need careful consideration.
Protect the property safely
Notify your insurer promptly and follow emergency officials' directions. Stay away from downed power lines, unstable trees, and damaged structures. Use qualified help for tarping, boarding openings, or other urgent protection work. Keep receipts and document conditions when safe.
Ask the insurer about preserving damaged materials that need removal. Necessary safety work should not wait for an adjusting consultation.
Get help reviewing your storm claim
Wheeler can discuss a new claim or questions about an estimate already received. We explain our services and fees before you decide whether to hire us.
Call 610-361-9704 or email info@wheeleradjustment.com. Tell us the property state, the storm date if known, and the status of your claim. We can help you understand the next steps for a supported review.